U.S. inflation data and the European Central Bank’s interest-rate decision will be the main focus next week in global markets, where oil prices and bond yields have risen. Volatility increased in markets this week, while energy costs and interest-rate expectations influenced pricing.
The United States’ resumption of attacks on Iran and rising oil prices intensified selling pressure in the bond market. The U.S. 10-year Treasury yield rose to 4.82%, its highest level since November 2023, while the 2-year yield reached 4.42%, its highest level since January 2025.
The 10-year Treasury yield ended the week at 4.79%, up 6 basis points. New York Fed President John Williams said inflation in the United States continued to slow as the impact of tariffs weakened and high energy prices did not spread to other service sectors.
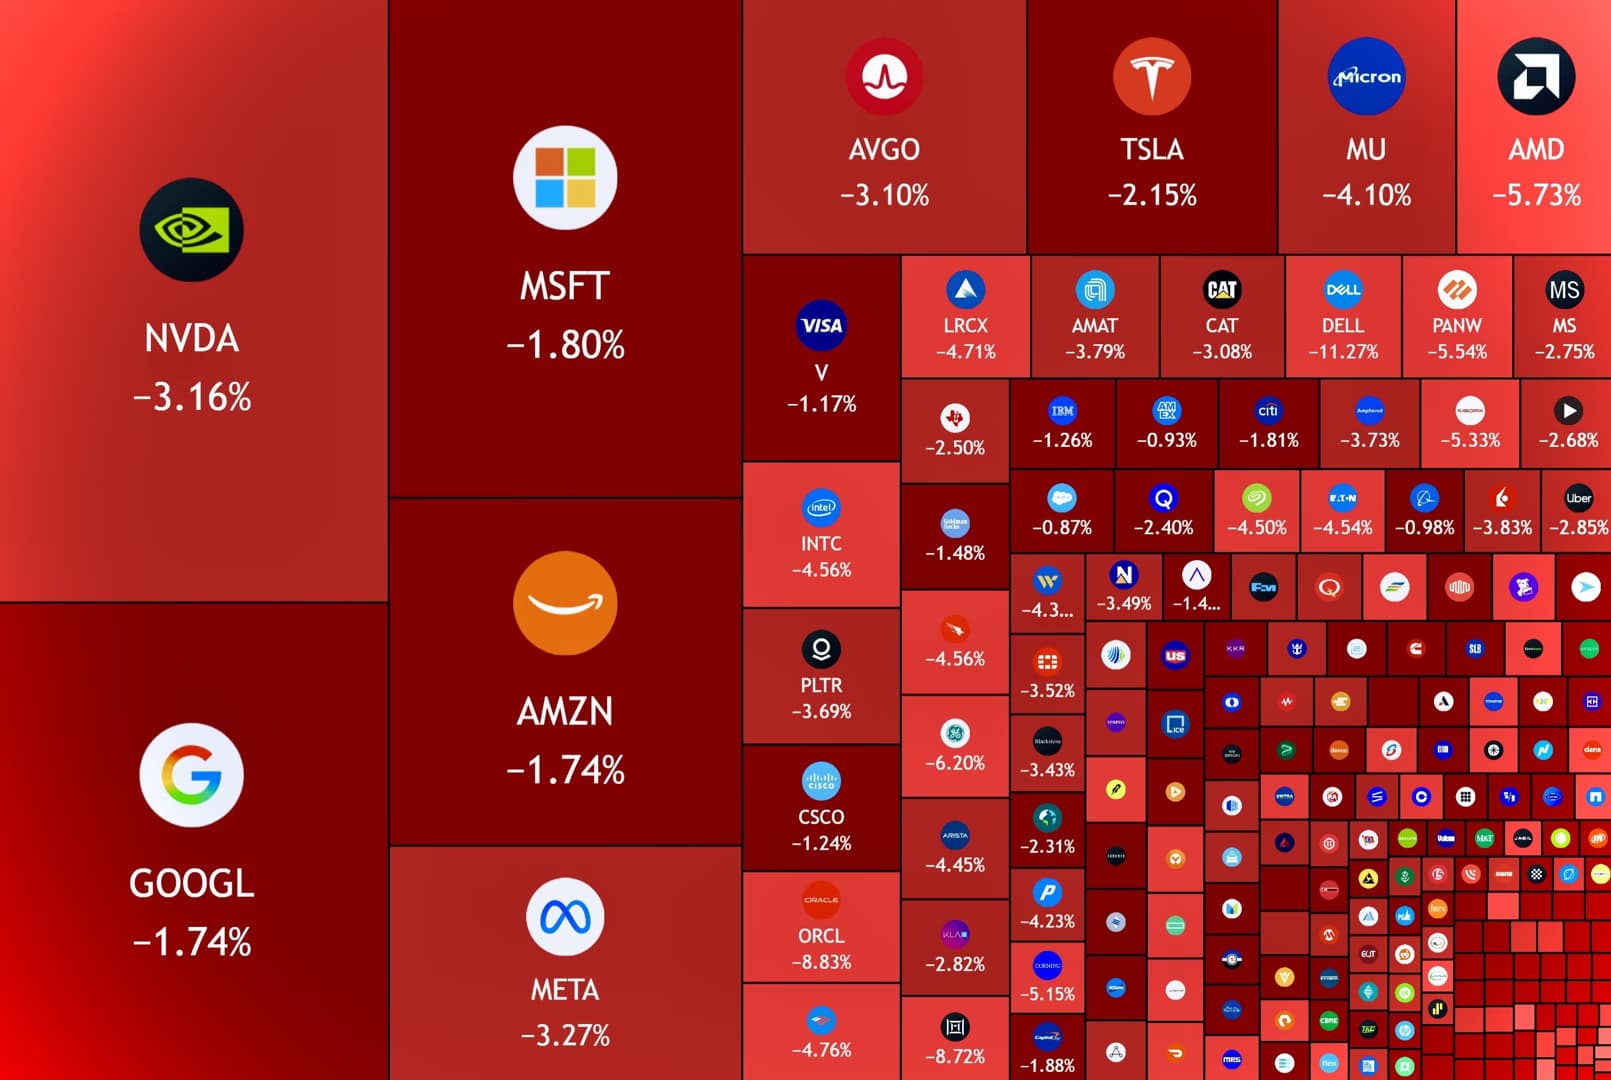
Federal Reserve Board Governor Christopher Waller said he could support keeping interest rates unchanged at this month’s monetary policy meeting if economic data showed that inflationary pressures were easing. However, stronger-than-expected nonfarm payrolls data revived expectations of an interest-rate hike and pushed stock markets lower on the final trading day of the week.
U.S. nonfarm payrolls increased by 162,000 in August. The unemployment rate remained unchanged at 4.1%, while employment data for June and July were revised upward by a combined 55,000.
U.S. President Donald Trump said the employment data had tripled every forecast except his own and stated that interest rates should be cut. Brent crude rose 6.4% on a weekly basis to $96.4 per barrel amid geopolitical risks linked to the Middle East.
Amid expectations of Federal Reserve rate hikes, gold prices fell 0.6% to close at $4,430 per ounce. The dollar index also declined 0.5% to 99.2 amid concerns about the United States’ fiscal position.
U.S. and European indexes move in different directions
On the New York Stock Exchange, the S&P 500 rose 0.09% and the Nasdaq gained 0.40% on a weekly basis. The Dow Jones index, however, lost 0.27%. In the United States, the Producer Price Index, Consumer Price Index and University of Michigan consumer sentiment index will be released next week.
European stock markets, except those in the United Kingdom, moved lower. Eurozone producer prices rose 1.6% month on month and 5.8% year on year in July, exceeding expectations, while consumer inflation rose to 3.3% in August, reaching its highest level in nearly three years.
Rising bond yields and concerns that military clashes in the Middle East could escalate limited risk appetite in Europe. Germany’s 10-year bond yield rose to 3.39%, the United Kingdom’s 10-year yield to 5.29% and France’s 2-year yield to 3.21%.
Isabel Schnabel, a member of the ECB’s Executive Board, said interest rates needed to be at higher levels. The ECB is expected to raise its policy rates at next week’s meeting, while energy prices became one of the bank’s main risk areas.
The FTSE 100 rose 0.06% on a weekly basis in the United Kingdom. France’s CAC 40 fell 1.46%, Italy’s MIB 30 declined 0.98% and Germany’s DAX dropped 1.97%. Next week, eurozone growth, inflation in Germany, the ECB’s interest-rate decision and industrial production in the United Kingdom will be monitored.
Energy prices weigh on Asian markets
Higher energy costs and elevated bond yields put pressure on Asian stock markets. Bank of Japan Governor Kazuo Ueda said they would continue examining whether economic and price developments were in line with expectations and assessing interest-rate increases.
Japan’s 5-year bond yield reached 2.31%, its highest level since 1994, while its 10-year yield rose to 3.017%, its highest level since 1995. On a weekly basis, South Korea’s Kospi fell 1.5%, Japan’s Nikkei 225 declined 2.09% and China’s Shanghai Composite Index dropped 0.27%. Hong Kong’s Hang Seng, however, rose 0.26%.
Next week, Japan will release growth and foreign trade balance data, China will publish inflation data, and Japan will announce industrial production figures.
Türkiye’s rate decision at the center of market attention
The BIST 100 index on Borsa Istanbul ended the week down 4.30% at 14,012.42 points. The dollar/Turkish lira exchange rate rose 0.40% from the previous weekly close to 48.4320.
Türkiye’s data and decision calendar for next week will include the Treasury cash balance, the Central Bank of the Republic of Türkiye’s interest-rate decision, industrial production, the balance of payments and the market participants survey.
According to economists’ expectations survey, the policy rate is expected to remain unchanged at 37% in September. The median year-end policy-rate expectation was calculated at 35%.