Expectations that the Federal Reserve will deliver a 25-basis-point rate hike at its two-day meeting beginning Wednesday caused global markets to move in different directions. Strong employment data, rising inflation expectations and Fed Chair Kevin Warsh's remarks on price stability also supported those expectations.
Warsh did not provide guidance on future rate decisions. As a result, his remarks after the meeting will be closely monitored for signals about the direction of monetary policy.
U.S. Treasury yield reaches highest level since 2007
The yield on the U.S. 10-year Treasury note rose to 5.04% on Tuesday, reaching its highest level since July 2007. After Treasury Secretary Scott Bessent said the U.S. Treasury market was the best-performing market in the world, the yield stabilized at around 5% on Wednesday.
In the U.S. Senate, the majority needed to bring the Clarity Act bill, which is planned to establish a comprehensive regulatory framework for the cryptocurrency sector, to the full Senate agenda was not secured. Following the development, Bitcoin fell 0.1% to $75,780, while shares of cryptocurrency exchange Coinbase dropped 10%.
November Brent crude futures fell 0.6% to $108.1 a barrel, pressured by an increase in U.S. inventories despite concerns over geopolitical risks. The price of gold also fell 0.6% to $4,321 an ounce.
Despite expectations of a rate hike, the U.S. dollar fell 0.1% to 99.6 amid fiscal concerns. The New York Stock Exchange ended Tuesday lower as rising Treasury yields weakened risk appetite.
U.S. stocks opened Wednesday higher
Meta announced that it had begun testing next-generation chips designed to run artificial intelligence models at lower cost and with less energy. The company's shares rose approximately 1% following the announcement.
The New York Fed's manufacturing index came in at 7.6 in September, below expectations. The American Automobile Association said the average diesel price reached a new record of $6.27 per gallon.
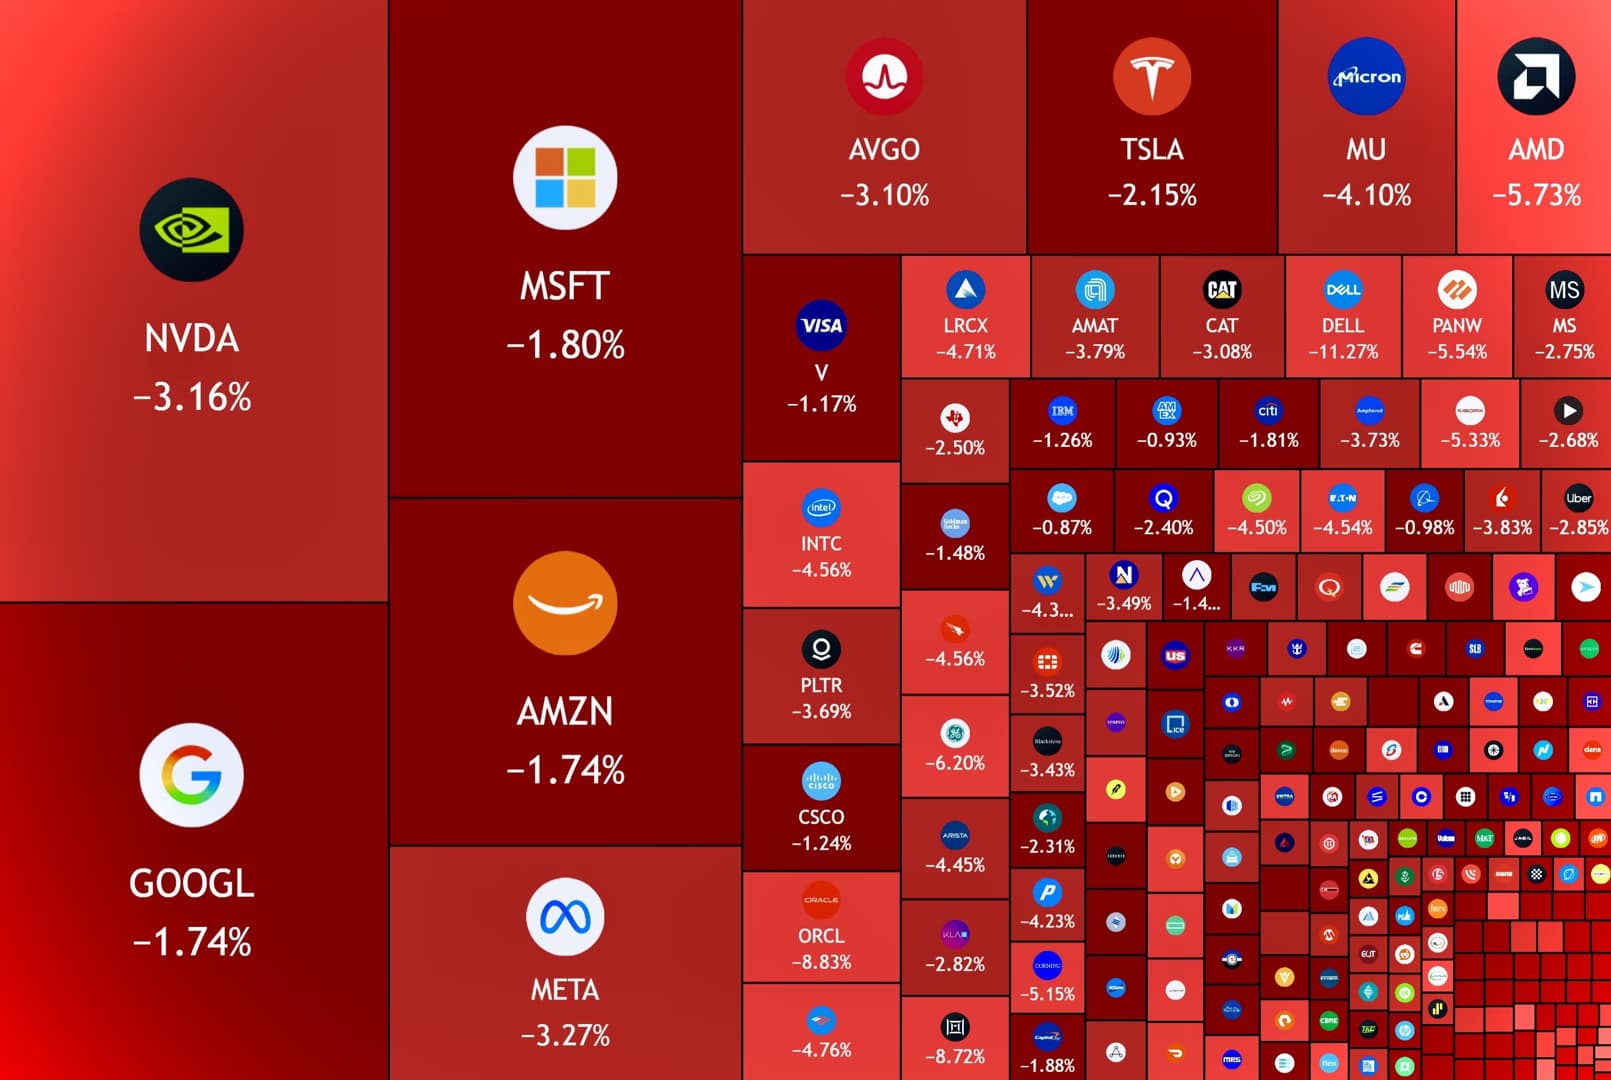
On Tuesday, the Dow Jones Industrial Average fell 0.63%, the S&P 500 declined 0.45% and the Nasdaq dropped 0.78%. U.S. stocks opened Wednesday's session higher.
Pressure from declines persists in European markets
Rising oil prices and selling pressure in bond markets continued to weigh on European stocks on Tuesday. Germany's ZEW Economic Sentiment Index rose to 34.7 in September from 34.2 in August but fell short of the expectation of 40.
Deutsche Bank shares fell 2.4%. The UK's FTSE 100 declined 0.37%, France's CAC 40 fell 0.34%, Italy's FTSE MIB 30 dropped 0.14% and Germany's DAX 40 lost 0.15%. European stocks presented a mixed picture on Wednesday.
Risk appetite strengthens in Asia
Easing selling pressure in bond markets increased risk appetite in Asian equity markets. Japan's exports rose 19.3% in August, while imports increased 28%; both figures came in above expectations.
Japan's trade deficit widened for a fourth consecutive month due to rising energy costs. The deficit increased from 638.3 billion yen to 1.1 trillion yen, equivalent to approximately $7.1 billion.
Toward the close of Wednesday's session, South Korea's Kospi rose 0.3%, Hong Kong's Hang Seng gained 0.1%, China's Shanghai Composite Index advanced 0.6% and Japan's Nikkei 225 climbed 0.3%.