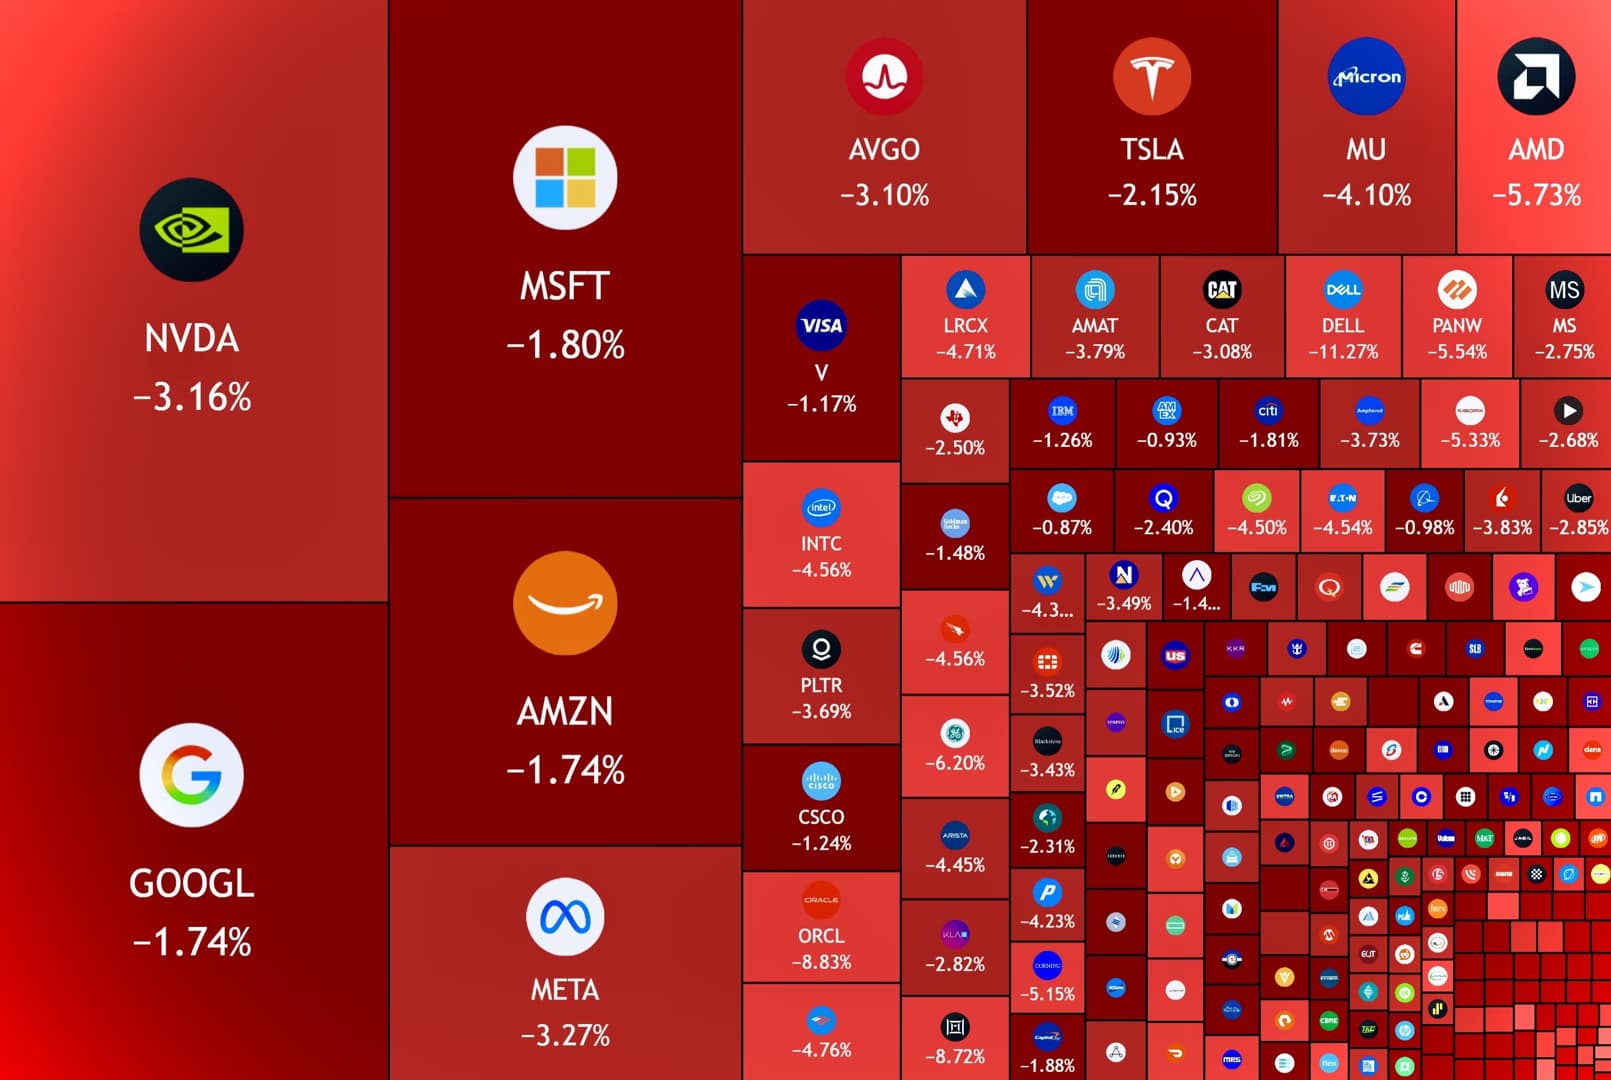
Rising yields in the U.S. Treasury market are reshaping investors' expectations for inflation and monetary policy. The 10-year Treasury yield climbed to 5.135% amid growing inflation concerns and weak demand at a Treasury auction, reaching its highest level since July 2007.
Yields also rose across other maturities. The two-year yield reached 4.947%, its highest level since May 2024, while the 30-year yield hit 5.43%, its highest level since June 2007.
Gap between short- and long-term yields narrows to 18 basis points
The spread between two- and 10-year U.S. Treasury yields narrowed to 18 basis points for the first time since February 2025. The convergence of short-term rate expectations with longer-term yields strengthened forecasts that monetary policy would remain tighter.
Analysts said the two-year Treasury yield is more sensitive to expectations for the Federal Reserve's monetary policy. The 10-year yield, meanwhile, is more affected by expectations about the persistence of inflation.
There have been periods when economic and financial stress increased as the 10-year Treasury yield rose above 5%. However, analysts emphasized that this level alone is not an indicator of a crisis. The 10-year inflation-protected Treasury yield also rose to 2.35%.
Rising oil prices add to inflationary pressure
As diplomatic contacts intensified during the 81st United Nations General Assembly in New York, no satisfactory progress was made in this regard. Concerns that geopolitical tensions between the U.S. and Iran could continue through the congressional midterm elections in November prevented the expected easing in oil prices.
Brent crude rose above $100 a barrel again. The possibility that the conflict could drag on once again highlighted in markets the link extending from oil prices to inflation and from interest rates to bond yields.
High oil prices and data pointing to continued strength in U.S. economic activity increased concerns that inflationary pressures could intensify. This environment also strengthened expectations that the Fed could take more forceful steps.
The U.S. manufacturing Purchasing Managers' Index rose to 57 in September, reaching its highest level in 52 months and exceeding market expectations. The services PMI reached its highest level in 59 months at 58.7.
Odds of a Fed rate hike rise to 70%
Analysts said that rising energy costs could lead the Fed toward tighter monetary policy while the U.S. economy remains strong. Market pricing indicated that the probability of the central bank raising its policy rate by 25 basis points next month had risen to 70%.
Tim Waterer, chief market analyst at KCM Trade, said that services and manufacturing PMI readings exceeding expectations in the U.S. and parts of Europe had revived concerns that central banks could raise interest rates more aggressively than previously anticipated.
Waterer said the shift in rate expectations had pushed the U.S. 10-year Treasury yield above 5.1%. He said investors faced the risk of persistently high inflation on one side and tighter monetary policy weakening economic growth on the other. Waterer added that this outlook had reduced market appetite for bonds and increased the risk premium demanded to carry government debt.